Most of us think investing is about finding the next big winner: the hot stock, the trending fund, or the tip from a friend who “made a fortune.” If you are searching for practical Howard Marks investing lessons, this book offers a completely different lens. What if the real secret isn’t picking winners at all, but rather avoiding big losses and staying calm while everyone else panics?
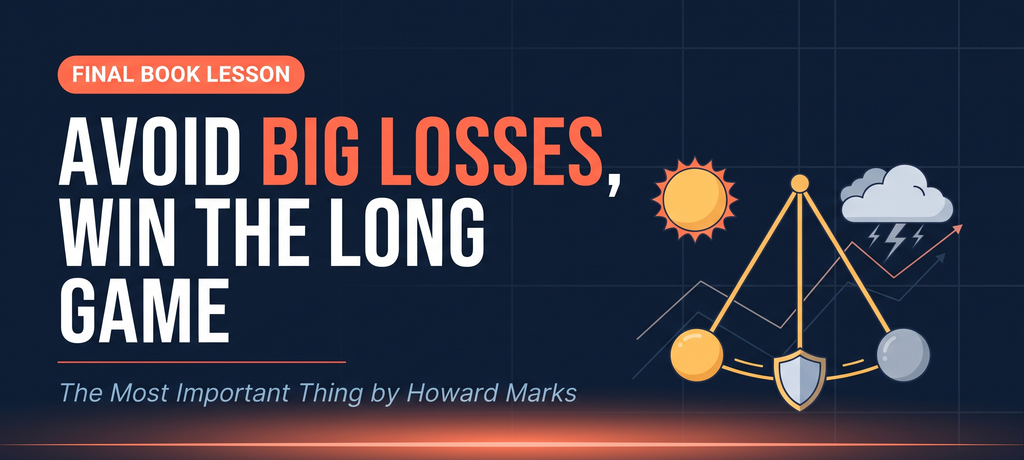
That’s the heart of The Most Important Thing by Howard Marks, co-founder of Oaktree Capital. Applying these timeless Howard Marks investing lessons helps you navigate uncertainty with a steady mindset. You can read more about his philosophy on the official Oaktree Capital Insights Page (Set this link to DoFollow in WordPress). It’s a book about deep thinking: how to understand risk, respect market cycles, and make sensible decisions when emotions run high. Warren Buffett has famously praised Marks’ investor memos, and this book pulls those masterclass ideas together.
For a mindful money blog, this is a perfect final chapter. Let’s break down the core Howard Marks investing lessons that matter most to help you protect your capital. 🌿
🧠 Lesson 1: Essential Howard Marks Investing Lessons on Second-Level Thinking
Marks talks about two ways to think about investing:
- First-level thinking: “This company is doing great, so I’ll buy the stock.”
- Second-level thinking: “This company is doing great, and everyone knows it, so the price may already be too high. What’s not yet priced in?”
First-level thinking is simple and shallow. Everyone does it. Second-level thinking asks what the crowd believes and where it might be wrong.
You can’t beat the market by thinking the same way as everyone else. That doesn’t mean being contrarian for the sake of it; it means asking better questions before you act.
Try this: Before any financial decision, ask yourself, “What am I assuming? What might I be missing? What if the popular opinion is wrong?”
⚠️ Lesson 2: Risk Is Not Just Volatility, It’s the Chance of Permanent Loss
Many people define risk as short-term price ups and downs. Marks sees it differently. The real risk is losing money permanently, or not being able to meet your goals when you need the cash.
A price that drops and later recovers is uncomfortable. But putting your emergency fund or your child’s education money in something volatile and needing it at the wrong time is real damage.
He also reminds us that risk is hardest to see when everything feels safe. When markets are rising and everyone is confident, danger is quietly building.
Try this: For each financial goal, ask, “When do I need this money? Can I afford to lose part of it?” Money you need soon belongs in safer places.
🎯 Lesson 3: Controlling Risk Matters More Than Chasing Returns
Here’s the twist: Marks argues that great investors aren’t the ones who take the most risk. They’re the ones who manage risk best.
You don’t need to win every year. Avoiding large losses matters because losses are hard to recover from. If your portfolio falls 50%, you need a 100% gain just to get back to even.
That’s why steady, sensible progress often beats dramatic swings. Skipping one terrible decision can be worth more than making ten brilliant ones.
🔄 Lesson 4: Everything Moves in Cycles
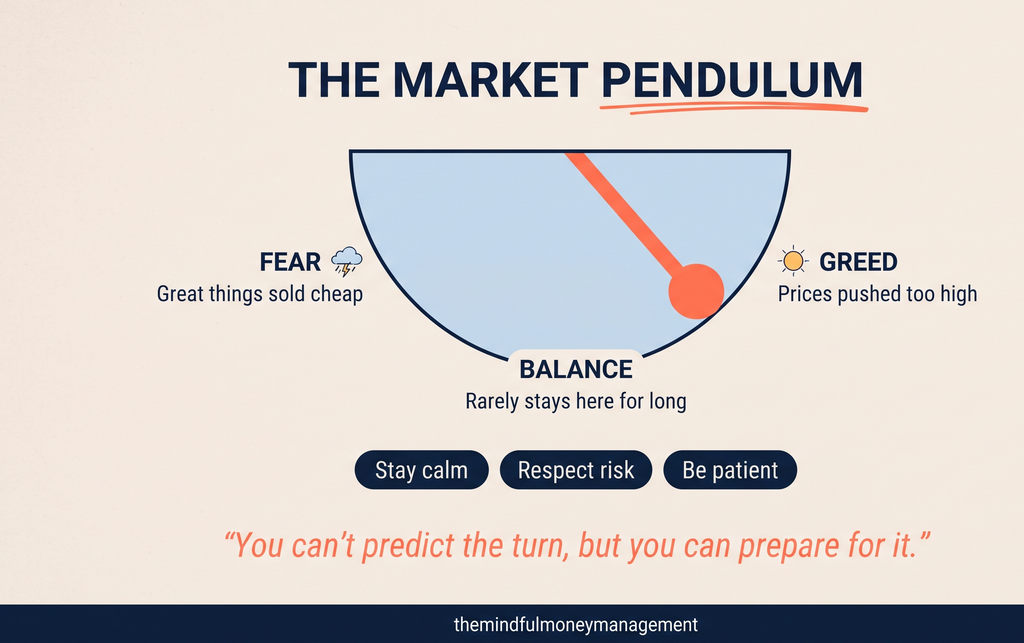
If there’s one theme running through the entire book, it’s this: markets move in cycles. Economies, credit, and investor moods swing back and forth like a pendulum, moving from too optimistic to too pessimistic and back again.
- When times are great, people take more risk and pay higher prices.
- When times are bad, fear takes over and good things get sold cheaply.
Marks’ message is that nothing goes up forever, and nothing stays down forever. You can’t predict exactly when a cycle will turn, but you can notice where you are in the market’s mood and adjust your behavior accordingly.
😨 Lesson 5: Your Emotions Are Your Biggest Enemy
Greed, fear, envy, and the urge to follow the crowd cause more investing mistakes than a lack of intelligence. Marks points out that when prices soar, people feel pressure to join in, and when prices crash, they rush to escape—usually at the worst possible moments.
True skill isn’t just knowledge; it’s temperament: staying steady when others aren’t.
Try this: Write down your personal investing rules when you’re calm—such as how much you invest monthly, when you rebalance, and what you’ll do in a crash. Then follow the plan, not your mood.
💎 Lesson 6: Price Matters as Much as Quality
A great company is not automatically a great investment. If you pay too much, even the best asset can disappoint. Conversely, a mediocre asset bought at a deeply discounted price can turn out well.
Marks stresses understanding value—what something is truly worth—and comparing it with its current price. The same logic applies at home: a “great deal” isn’t a deal if you didn’t need it, and a premium product isn’t worth it if the price far exceeds its utility.
🔮 Lesson 7: Be Humble About the Future
Nobody knows what markets, interest rates, or the economy will do next. Marks is refreshingly honest about how poor forecasting is, even among industry experts.
So instead of trying to guess the future, prepare for a range of outcomes. Build a plan that survives surprises. This is why the mindful money basics matter so much: an emergency fund, sensible insurance, diversified savings, and living below your means. They keep you steady when life doesn’t follow the forecast.
🌿 How This Fits Mindful Money Management
This book is a beautiful match for our philosophy of intentional money habits:
- Mindful spending protects your everyday cash flow.
- Mindful saving builds your safety net.
- Mindful investing, the Marks way, means understanding risk, respecting cycles, and staying calm. (You can explore more on asset allocation in our guide on the 50/30/20 budgeting rule.
It’s not about being clever. It’s about being thoughtful, patient, and prepared.
✅ Your Howard Marks Action Checklist
Pick one or two items to start this week:
- ☐ List each financial goal with its timeline (short-term, medium-term, long-term)
- ☐ Check that money needed within 3–5 years isn’t placed in high-risk options
- ☐ Write down your personal investing rules for calm and crash moments
- ☐ Before your next money decision, ask the second-level question: “What might everyone else be missing?”
- ☐ Review your emergency fund: is it enough for 3–6 months of expenses?
- ☐ Unfollow one source of hype or panic that pushes you into rushed decisions
💬 Final Thoughts
The Most Important Thing isn’t about beating the market with secret tricks. It’s about thinking clearly, respecting risk, staying patient, and protecting yourself from your own emotions. You don’t need to predict the future; you just need to prepare wisely for it.
If you remember only one core takeaway from these Howard Marks investing lessons, let it be this: the goal isn’t to avoid every mistake, but to avoid the ones you can’t recover from. That mindset alone can change how you handle money for life.
(Disclaimer: This post shares lessons from a book for educational purposes and is not personal financial or investment advice. All investments carry risk. Please consider your own circumstances and consult a qualified professional before making decisions.)
🗨️ Let’s Talk
When markets get scary, do you tend to stay calm, or feel the urge to act right away? Share your honest answer in the comments. No judgment, we’re all learning together. 💛
Enjoyed this? Catch up on our previous insights from Die With Zero, The Almanack of Naval Ravikant, and The Psychology of Money, or follow along for more lessons from the 100-day book challenge as we build a wealthier life together!