Picture the wealthiest person in your neighbourhood.
Most of us picture the same thing: the big car, the imported furniture, the holidays abroad, the wedding that people talk about for years. Money you can see.
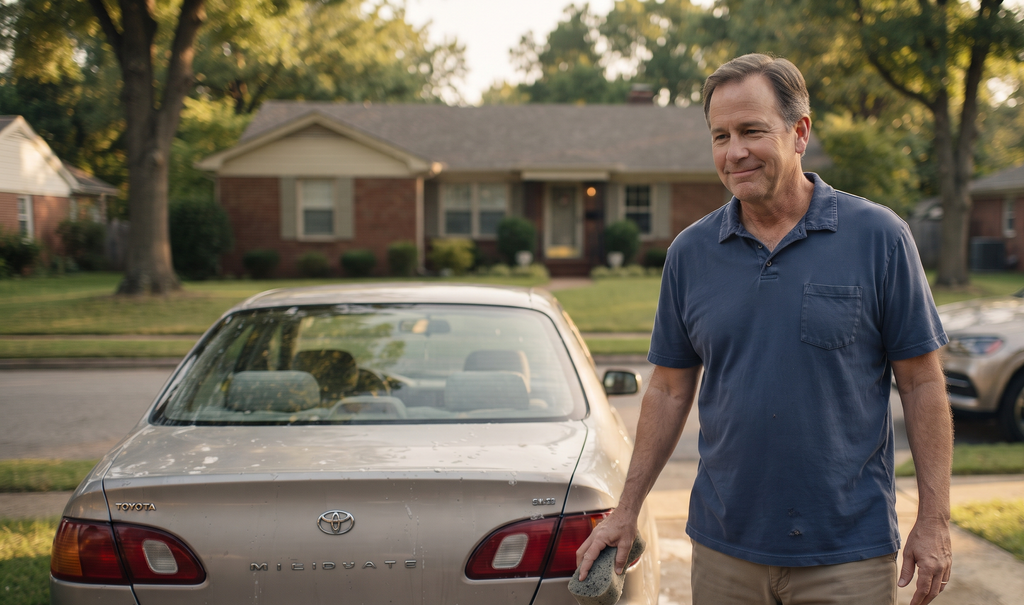
When you study the millionaire next door lessons from Thomas Stanley and William Danko’s decades of research (detailed further on The Thomas Stanley Official Website), you discover someone entirely different — someone who bought a modest house twenty years ago and never moved, who drives a car with a lakh of kilometres on it, who has no idea what a designer handbag costs and doesn’t care.
That’s the whole book in one sentence: the people who look rich and the people who are rich are usually not the same people.
Let’s unpack what that actually means for you and me.
💰 Income is what you earn. Wealth is what you keep.
This is the distinction the book hammers on, and it’s the one most of us get wrong.
A high salary is not wealth. A high salary is raw material. What you do with the gap between what comes in and what goes out — that’s wealth.
As explored in our deep-dive on The Psychology of Money Lessons, spending money to show people how prosperous you are is the fastest way to stay broke. Stanley’s research kept finding people earning very impressive incomes who had almost nothing behind them. Every raise got absorbed within months. Bigger house, bigger EMI, bigger lifestyle, same empty balance sheet. He called this “big hat, no cattle” — all the outward signals of wealth, nothing underneath holding them up.
And right alongside them were people earning far less who had quietly accumulated real money, because their lifestyle never expanded to swallow their income.
The question isn’t “how much do you make?” It’s “how much of it is still yours a year later?”
📊 The formula that tells you where you actually stand
Here’s the most useful practical tool in the entire book. It’s a rough benchmark, not gospel — but it’s clarifying.
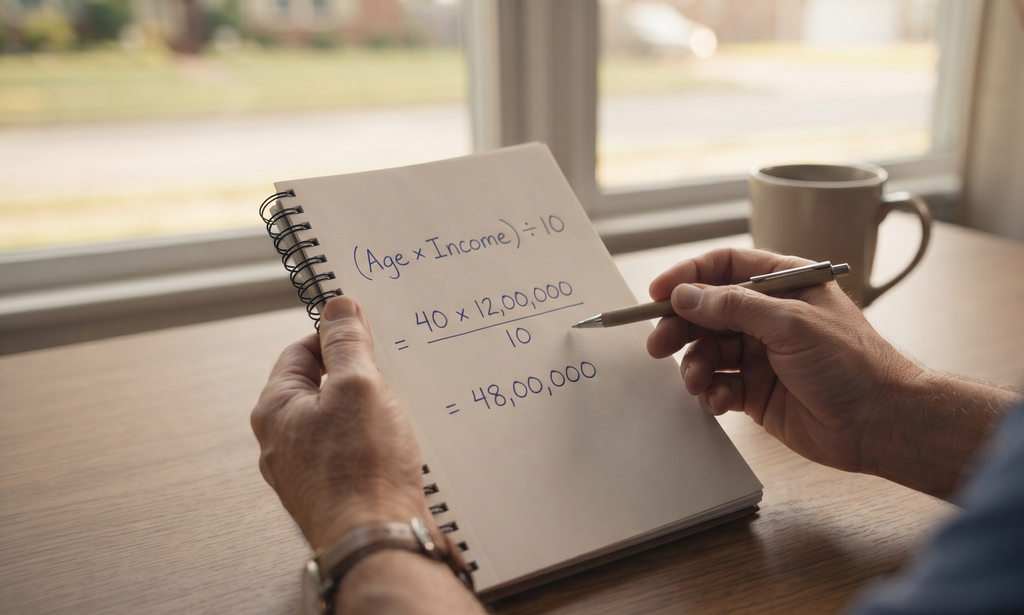
Expected net worth = (your age × your annual pre-tax household income) ÷ 10
So if you’re 40 and your household brings in ₹12 lakh a year:
40 × 12,00,000 ÷ 10 = ₹48 lakh
That’s your baseline. Then Stanley sorts people into three groups:
- PAW — Prodigious Accumulator of Wealth: you have double the expected figure or more
- AAW — Average Accumulator of Wealth: you’re roughly at it
- UAW — Under Accumulator of Wealth: you have half or less
The formula works in any currency — rupees, dollars, dirhams. It doesn’t matter.
If you want to understand why this number matters more than your monthly paycheck, take a look at our guide on Why Your Net Worth Matters More Than Your Salary.
A quick caveat before you go calculate it and feel terrible: this benchmark is harsh on people early in their careers, because it multiplies by age when you’ve barely had time to save anything. If you’re 25, ignore the number and just watch the direction of travel. It’s most honest for people in their 40s and 50s.
Run it anyway. Even if the number stings, it tells you something no amount of vibes-based budgeting will.
🛡️ Great offence, terrible defence
Stanley describes money management in two halves.
Offence is earning — your salary, your business, your side income.
Defence is keeping — budgeting, avoiding lifestyle inflation, investing steadily, not leaking money to things that don’t matter to you.
Most people obsess over offence. Get the promotion. Land the bigger client. Raise the rates. And offence matters! But his millionaires almost universally played exceptional defence. Many of them played merely decent offence.
You can absolutely out-earn a bad savings rate — but you have to out-earn it forever, and one bad year takes the whole thing down.
Defence compounds quietly and never asks for a raise.
🏠 The seven habits Stanley kept finding
Across all his interviews, the same patterns kept showing up. These are the load-bearing walls of the book:
- They live well below their means. Not slightly below. Well below. The gap is the point.
- They spend time, energy and money in ways that build wealth. Not in ways that display it.
- They value financial independence over social status. Given a choice between looking successful and being free, they pick free every single time.
- Their parents didn’t fund their adult lifestyle. More on this below — it’s the most uncomfortable chapter.
- Their adult children are financially self-sufficient. They raised kids who could stand on their own.
- They’re good at spotting opportunities. Business, market, career — they notice where value is being created.
- They chose the right occupation. Often a boring one. Extremely often a boring one.
That last point deserves a moment. Stanley found millionaires running scrap metal businesses, pest control services, dry cleaning chains, small manufacturing units. Unglamorous work that nobody posts about. Meanwhile many high-status professions were full of people with impressive titles and thin balance sheets, because the profession came with an expected lifestyle attached.
Prestige has a price tag. Boring businesses don’t.
🚗 How they actually spend
Some details from the research that stuck with me:
- A large share bought used cars, and held them for years. Not because they couldn’t afford new — because a car is a depreciating box and they knew it.
- Most had never spent anywhere near what you’d expect on a watch, a suit, or a pair of shoes. Their upper limits were modest and they knew their limits precisely.
- They bought homes they could comfortably afford, in ordinary neighbourhoods, and stayed put. No upgrading every time income rose.
That last one is the quiet killer for most of us. Moving up a neighbourhood doesn’t just raise your rent or EMI. It raises everything around it — the school, the car in your driveway, the gifts you give, the restaurants your new friends pick. One decision drags a dozen others up with it.
👨👩👧 The chapter nobody likes: Economic Outpatient Care
Stanley uses this phrase for the ongoing financial support that well-off parents give their adult children. The down payment. The car. The “just this once” transfer that becomes monthly.
His finding was blunt: adult children who receive regular financial gifts tend to accumulate less wealth than those who don’t. The support props up a lifestyle above what their own income can sustain, so they never develop the muscle of living within their means — and they often end up dependent on the next gift arriving.
This one is genuinely tricky in our context, where supporting family is woven into how we live and isn’t going anywhere. I don’t think the answer is to withhold help. I think the honest takeaway is narrower: money given to fund a lifestyle weakens. Money given to fund capability strengthens.
Education, a business seed, a medical emergency, a genuine leg-up — different category entirely. Topping up someone’s monthly gap indefinitely is the thing Stanley was warning about.
⏳ The habit underneath all the other habits
Here’s the correlation that ties the book together: the millionaires in his research spent significantly more hours planning their finances than the under-accumulators did.
Not trading. Not chasing. Planning. Knowing their numbers. Setting targets. Reviewing where money went. Many could tell him almost exactly what they spent on groceries or clothing in a year.
The under-accumulators, meanwhile, often had no idea — and had no budget, because “we earn enough that we don’t need one.” Stanley’s rebuttal is perfect: people who become wealthy budget precisely because they want to stay that way.
Attention is the actual asset here. Everything else follows from it.
✅ Your this-week checklist
- Calculate your expected net worth with the formula. Write the real number down.
- Pick one expense that exists mainly for how it looks to others. Cut it or shrink it.
- Find your last three months of spending and total just two categories: food and shopping. Most of us are off by 40%.
- Name one thing you’d upgrade the moment your income rises — and decide now that you won’t.
- Schedule one hour a month for money planning. Actually put it in the calendar.
⚖️ Where the book shows its age
Honest note, because I don’t want to hand you this as scripture.
The research is from the 1990s, and some of it has aged awkwardly. Housing costs relative to income have moved dramatically since then, so “just buy a modest house” is doing a lot of heavier lifting today than it did in 1996. There’s also a survivorship problem — Stanley studied people who became millionaires and found frugality, but plenty of frugal people never get there, because frugality alone isn’t a wealth engine. And it underweights how much a rising income genuinely changes the maths.
Defence without offence is slow. Offence without defence is fragile. You want both.
But the core insight has not aged a day: most of what we call “looking wealthy” is just an expensive way of staying broke.
The richest person on your street isn’t the one you’d guess. She’s the one who stopped caring what you’d guess.
💬 Over to you: Run the net worth formula and tell me — were you above the line or below it? No judgement here, mine surprised me too.